The -function is only defined by its behaviour in integrals:
where the limits and are positive and as large or small as we want; the integration simply has to span the point on which the -function is centred.
The following equivalences may also be proved by changing variables in the corresponding integral (an appropriate integration range is assumed for compactness of notation):
Note that the dimensions of a -function are the inverse of those of its argument, as should be obvious from the first equation.
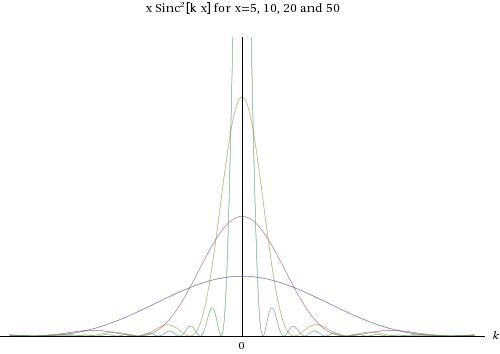
We encounter two functions which tend to -functions:
In both cases, as the function tends to zero unless , at which point it tends to , so it looks like an infinite spike at .
That the normalisation (with respect to integration w.r.t ) is correct follows from the following two integrals: and . The second of these follows from the first via integration by parts. The integral may be done via the contour integral below:

As no poles are included by the contour, the full contour integral is zero. By Jordan’s lemma the integral round the outer circle tends to zero as as decays exponentially in the upper half plane. So the integral along the real axis is equal and opposite to the integral over the inner circle, namely of the residue at , . So the imaginary part, the integral of , is .